Connect each vehicle to its records
Inventory valuation needs purchase cost, relevant additional costs, condition and saleability under the accounting framework. Use a clear identifier such as the chassis number to reconcile physical stock, sales, workshop and ledger records.
Distinguish location from ownership
Vehicles on site may be held on consignment or for customers, while owned vehicles may be in transit. Contracts, delivery evidence and financing establish the relevant rights and risks, especially around year-end.
Document ageing and demonstrator use
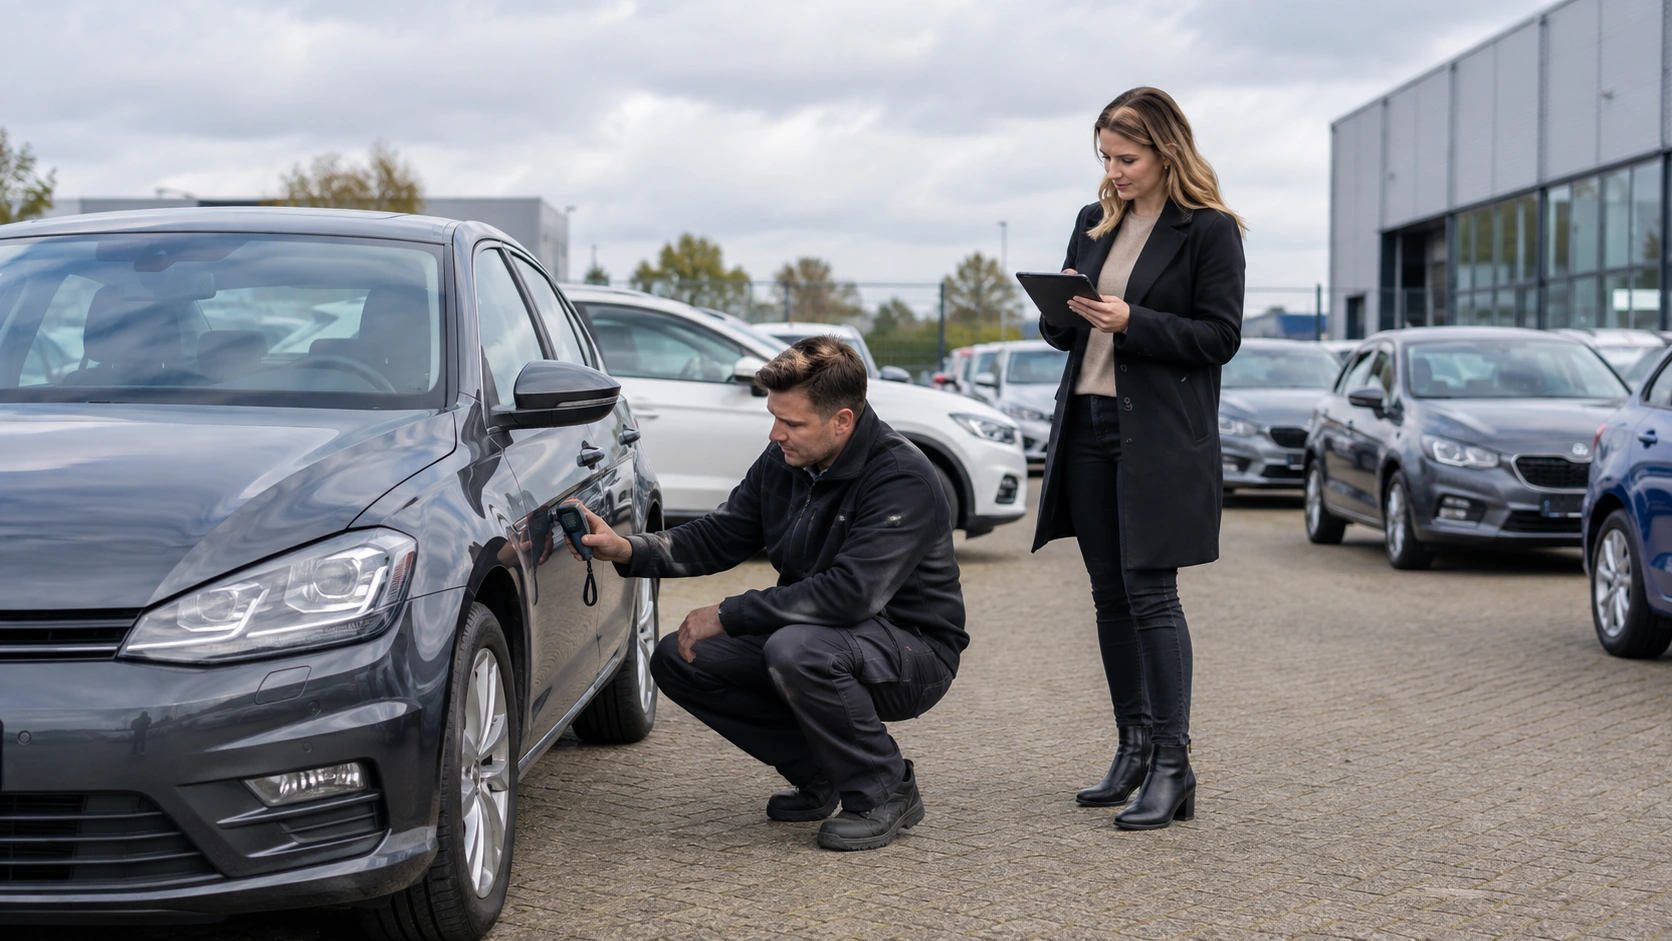
Long holding periods, damage, model changes and market demand can affect expected proceeds. Support any adjustment with selling-price and repair-cost evidence. Keep demonstrator mileage and use history current. VAT classification and commercial margin are separate: a correct VAT code does not prove that all vehicle costs are included.
Source and background: De jaarrekening waar de ondernemer op wacht.